Personal Finance Tips 2026: 9 Habits That Build Wealth
The best personal finance tips are rarely complicated — they are simply consistent. In 2026, with prices still shifting and interest rates in flux, the households that thrive are not the ones earning the most. They are the ones who turn a few small habits into automatic routines. This article shares nine of those habits, drawn from years of trial, error, and steady progress.
Think of what follows as a practical playbook rather than a lecture. You do not need a finance degree, and you do not need to overhaul your life overnight. You need direction and a little repetition.
Start With a Budget You Will Actually Keep
A budget is not a punishment; it is a plan for spending on what you value. The reason most budgets fail is that they are too strict. Aim for a framework loose enough to survive real life.
The popular 50/30/20 split is a solid starting point: half your take-home pay for needs, a third for wants, and a fifth for saving and debt. Adjust the ratios to your reality rather than forcing your reality to fit them.
Track Before You Cut
Spend two weeks simply recording where money goes before slashing anything. Awareness alone tends to trim wasteful spending, because you finally see the patterns hiding in plain sight.
Automate Your Savings First
Paying yourself first is the single most powerful habit on this list. Schedule an automatic transfer to savings the day your paycheck lands, so the money leaves before you can spend it.
- Set up direct deposit to split a percentage straight into savings.
- Use round-up features to sweep spare change into a goal.
- Name each savings bucket — “emergency,” “travel,” “new laptop” — for motivation.
- Increase the transfer by 1% every few months; you will barely notice.
Build an Emergency Fund That Lets You Sleep
Life delivers surprises: a car repair, a medical bill, a sudden move. An emergency fund keeps those events from becoming debt spirals. Start with a modest goal and grow it over time.
- Save a starter cushion of $1,000 as fast as you can.
- Build toward one month of essential expenses.
- Stretch to three months once other goals are on track.
- Keep it in a separate, high-yield account you will not touch casually.
How Much Should You Save Each Month?
There is no universal number, but a useful target is 20% of take-home pay across savings and debt payoff combined. If that feels impossible today, start at 5% and climb. The federal financial-education hub MyMoney.gov offers free worksheets to help you set a realistic rate for your situation.
Remember that consistency beats intensity. Saving a steady 10% for a decade outperforms sporadic bursts of 30% followed by nothing.
Tackle Debt Strategically
Not all debt is equal. High-interest credit-card balances deserve urgent attention, while a low-rate loan can be paid on schedule. Two proven methods help you stay motivated.
| Method | How It Works | Best For |
|---|---|---|
| Avalanche | Pay highest interest rate first | Saving the most money |
| Snowball | Pay smallest balance first | Staying motivated |
Pick the method whose psychology fits you. The mathematically optimal plan is worthless if you abandon it in month two.
Put Technology to Work
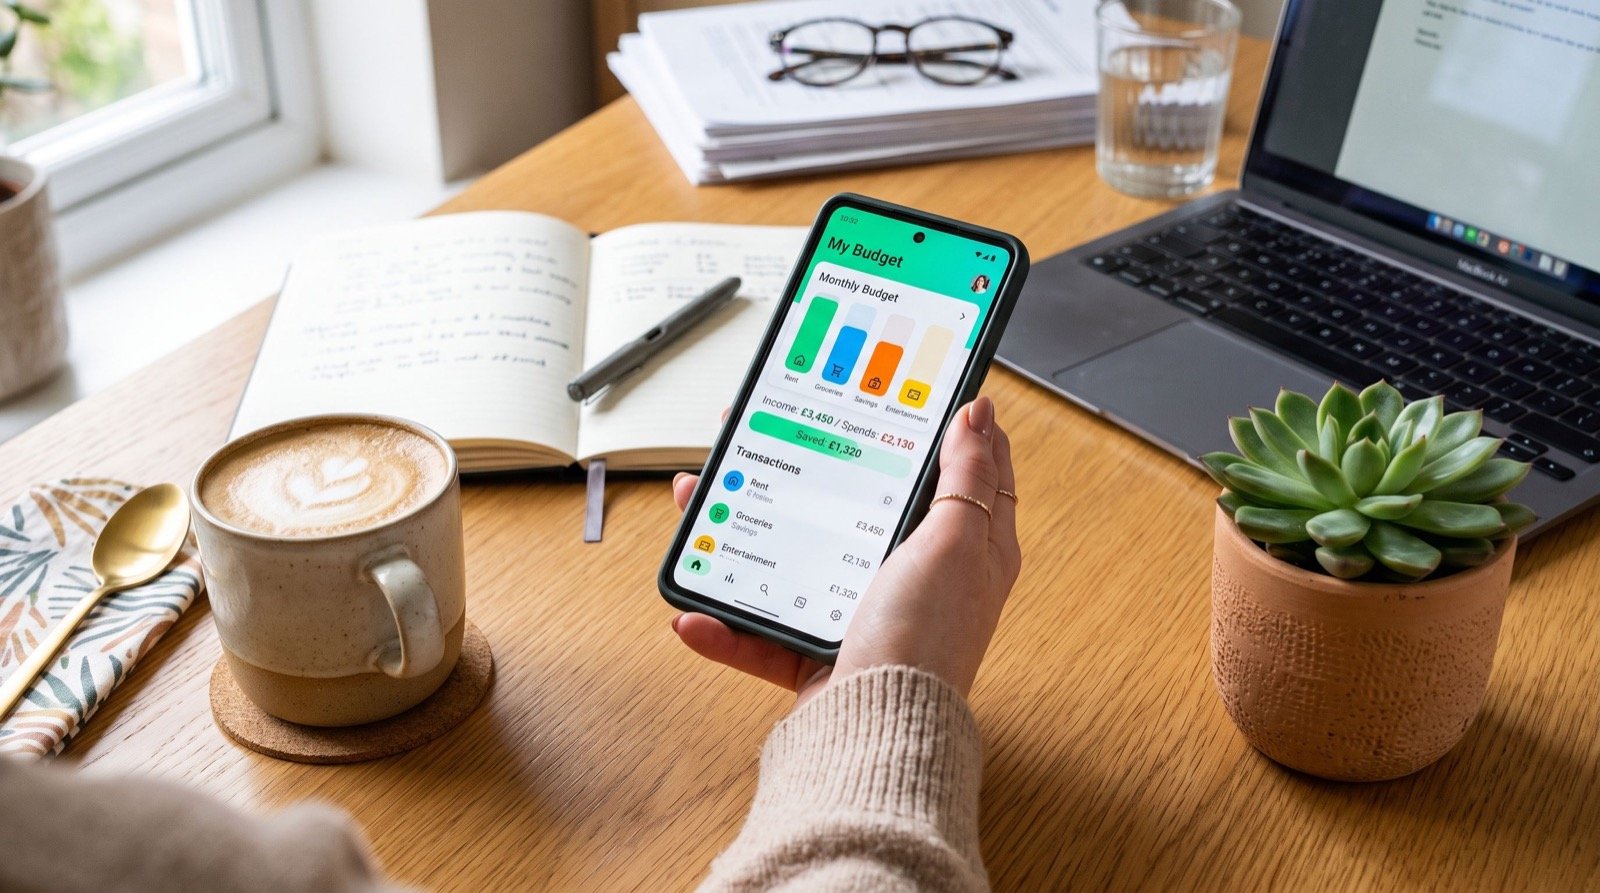
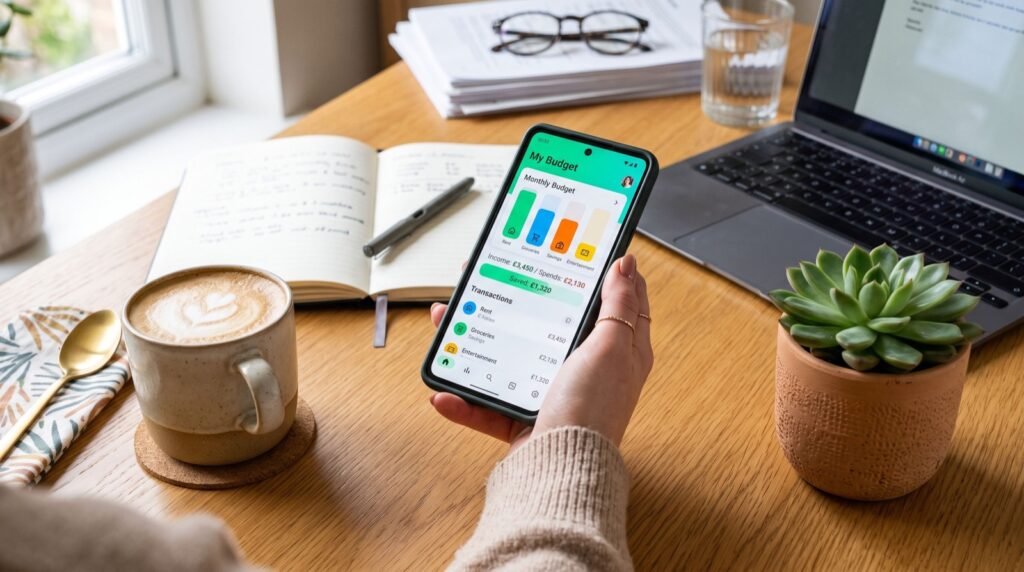
Modern tools make good habits nearly effortless. The right money apps can categorize spending, flag subscriptions you forgot, and automate transfers so discipline runs in the background. Pair them with the broader personal finance tips in this guide and each reinforces the other.
Invest for the Long Haul
Once your emergency fund is solid and high-interest debt is gone, investing turns saving into wealth. Low-cost index funds let ordinary earners participate in market growth without picking individual stocks. Before you begin, the U.S. Securities and Exchange Commission’s Investor.gov explains fees, compounding, and risk in plain language.
Time in the market matters more than timing the market. Start small, stay consistent, and let compounding do the heavy lifting over the years.
Don’t Forget Retirement Accounts
If your employer offers a matching contribution, capture it fully — that match is an instant, guaranteed return you will not find anywhere else. Beyond the match, tax-advantaged accounts let your money grow while shrinking your annual tax bill. Even modest contributions in your twenties or thirties can dwarf larger ones started later, thanks to decades of compounding.
Protect and Grow Your Credit Score
Your credit score quietly shapes the rates you pay on everything from cards to car loans, so guarding it is a habit worth forming early. The good news is that the levers are simple and within your control.
Pay every bill on time, since payment history is the single largest factor. Keep your credit utilization — the share of available credit you use — below 30%, and lower is better. Avoid opening several new accounts at once, and check your reports regularly for errors you can dispute.
Small, boring consistency wins here too. A single missed payment can linger on your report for years, while a long stretch of on-time payments steadily lifts your standing and unlocks cheaper borrowing when you truly need it.
Plan Ahead for Big Expenses
Major costs rarely arrive without warning, so give them their own savings goal. When my family planned a villa relocation, we budgeted months in advance and hired the reliable local experts without touching our emergency fund. Anticipating big expenses turns stressful surprises into simple line items.
Frequently Asked Questions
What is the best personal finance tip for beginners?
Automate your savings. Setting up an automatic transfer on payday removes willpower from the equation and guarantees you save before spending. It is the one habit that quietly powers all the others.
How do I stick to a budget long term?
Keep it flexible, review it monthly, and leave room for fun. A budget that forbids every small pleasure collapses quickly, while one aligned with your values becomes a habit you actually maintain.
Should I save or pay off debt first?
Do both in parallel. Build a small emergency cushion so surprises do not create new debt, then attack high-interest balances aggressively while saving a steady amount each month.
How often should I review my finances?
A quick monthly check-in and a deeper quarterly review work well for most people. Track your net worth over time so you can see progress and adjust goals as your life changes.
Final Word
Wealth is built quietly, one repeated choice at a time. Budget with intention, automate your savings, clear costly debt, and invest for the long run. Apply these personal finance tips throughout 2026, stay patient, and watch small habits compound into lasting financial confidence.